Incentivized Review Markup: Google and FTC Audit
Audit experience, incentives, disclosures, visible-page parity and aggregate math with a 22-field review markup ledger.
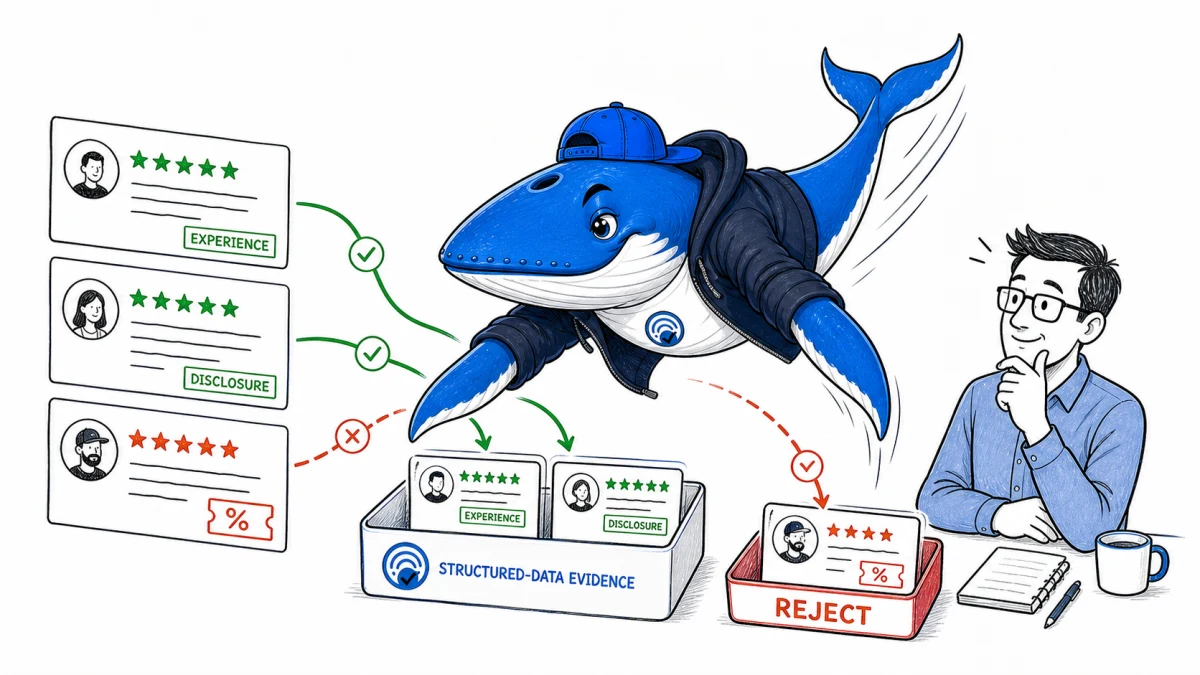
Updated August 29, 2026: Google now says not to include fake or undisclosed incentivized reviews on a page or in review structured data. Its examples cover reviews that are not based on a genuine experience and reviews written for money, discounts, vouchers, free products or another benefit when that incentive is not clearly and prominently disclosed.
Direct answer: do not solve this with a JSON-LD edit alone. First prove the experience, incentive and disclosure on the visible page. Then decide whether the review belongs in Review markup and in the visible AggregateRating. Google eligibility, platform rules and consumer-protection duties are separate gates; passing one does not guarantee the others.
What Google’s review-snippet rule now says
Google’s review-snippet documentation added two concrete exclusions: reviews without a genuine product or service experience, and incentivized reviews whose benefit is not clearly and prominently disclosed. That is narrower than saying every compensated review is automatically eligible after disclosure. The page must still satisfy the supported-type, visible-content, item-specific and technical requirements, and a valid result is never guaranteed to display.
Google also says not to aggregate reviews or ratings copied from other websites. For LocalBusiness and Organization, review features are limited to sites that collect reviews about other businesses or organizations; self-serving review markup remains outside the eligible pattern. These rules apply in addition to the new incentive language.
| Gate | Question | Evidence to preserve | Typical failure |
|---|---|---|---|
| Visible review | Did a real person have the stated experience, and can readers see the material relationship? | Submission, order or access record; exact disclosure; rendered-page capture | Vague “gifted” label or no experience record |
| Google markup | Does the page, item type and marked data follow Search Central rules? | Rendered HTML, JSON-LD, eligible review set, aggregate calculation | Hidden data, imported ratings or self-serving business markup |
| Law and platform policy | Is the solicitation and presentation permitted where the review appears? | Jurisdiction, platform terms, incentive offer and moderation record | Positive-sentiment condition or avoidable disclosure |
Classify each review before touching schema
Use the review as the unit of analysis. A sitewide disclosure page cannot tell a reader which reviewer received what, and it cannot repair a review that was fabricated or conditioned on positive sentiment. The safest workflow records the underlying experience and benefit before an editor decides whether the review may appear or be marked up.
| Observed case | Visible-page action | Markup action |
|---|---|---|
| No genuine experience can be documented | Reject as a review | Exclude from Review and aggregate math |
| Genuine experience; no material benefit | Publish with normal authorship and moderation | Evaluate against all Google requirements |
| Genuine experience; benefit clearly disclosed | Place plain-language disclosure with the review | Evaluate, but do not assume rich-result eligibility |
| Benefit hidden, vague or behind an action | Repair before release | Exclude until the visible disclosure is adequate |
| Reward requires a positive or five-star review | Reject and escalate | Exclude; disclosure does not cure sentiment conditioning |
| Rating copied from another website | Cite it only as permitted editorial evidence | Do not aggregate it into Google review markup |
“Gifted,” “partner,” an icon or a tooltip may not explain the relationship. Prefer direct wording that identifies the benefit, such as “The reviewer received this product free” or “The reviewer was paid for this review.” The exact language still needs a context-specific legal and platform review.
Keep Google eligibility separate from FTC requirements
For US-facing programs, the Federal Trade Commission says incentives must not be expressly or implicitly conditioned on positive sentiment. It also warns that individual disclosures may not prevent deception when incentivized ratings materially lift the aggregate score. The FTC’s Consumer Reviews and Testimonials Rule addresses buying positive or negative reviews, insider relationships and other practices; separate Endorsement Guides and FTC Act principles can also apply.
The FTC describes a required disclosure as clear and conspicuous and, for the relevant rule provision, unavoidable: a consumer should not need to click a link or hover over an icon to see it. That makes a disclosure beside the review materially stronger than a generic footer or policy link. The precise legal duty depends on the facts and jurisdiction, so this workflow is an evidence-control method, not legal advice.
Download the review disclosure and markup ledger
Use the review disclosure and markup ledger (CSV) to preserve one decision record per review. The template has 22 fields covering experience evidence, incentive type, exact disclosure, visibility, sentiment conditioning, source platform, self-serving business status, markup inclusion, aggregate inclusion, owner and re-audit date.
The four included rows are explicitly labelled examples and should be removed before production use. They demonstrate four different outcomes: disclosed free product, missing experience evidence, an impermissible positive-sentiment condition, and a rating imported from another site. Do not copy their decisions blindly; replace them with evidence from your own program.
Minimum record for each review
- A durable review or submission identifier and the specific reviewed item.
- Evidence that the reviewer used, bought, tested or otherwise experienced that item.
- Every material benefit and whether it depended on a positive rating or statement.
- The exact disclosure text and where a reader sees it without extra action.
- The visible-page, markup and aggregate-rating decisions, each with a reason.
- An accountable owner, review timestamp and re-audit trigger.
Recalculate the aggregate from the same eligible set
Removing an ineligible review without updating the visible count, average and structured data creates a second mismatch. Define one eligible review set and calculate every representation from it. If ratings use different scales, normalize them only with a documented formula and retain the original value.
| Representation | Required parity check | Evidence |
|---|---|---|
| Visible review list | Every included review is rendered and item-specific | Review IDs in page order |
| Visible average and count | Reproduces from the eligible visible IDs | Calculation export and rounding rule |
AggregateRating | ratingValue and count match the page | Rendered JSON-LD or microdata |
Individual Review nodes | Author, rating and reviewed item match visible content | Review-to-node mapping |
Google’s general structured data guidelines say not to mark up content that readers cannot see. They also warn that omitting visible reviews from a multi-review page can mislead people who expect the rich result to represent the page. Treat completeness and visibility as release requirements, not post-launch cleanup.
Run the rendered-page parity test
- Open the final page in a normal browser and locate the item, review text, author, date, rating and incentive disclosure.
- Confirm that the disclosure remains visible on mobile, after consent layers load, and when a deep link opens directly at the review.
- Inspect the rendered structured data rather than only the CMS field or source template.
- Map each marked review to its ledger record and exclude every rejected or unresolved entry.
- Reproduce the aggregate count and rating from the included record IDs.
- Test normal, disclosed-incentive, rejected and edited-review cases.
- Validate syntax in Google’s Rich Results Test, then inspect the live URL in Search Console after release.
The schema decision guide explains why valid schema vocabulary, Google feature eligibility and actual display are different states. Search Engine Answer’s commercial disclosure policy documents our own separation of editorial and commercial relationships.
Release a sample, then monitor the program
Do not deploy a new review program across every product at once. Release a small representative set that includes an ordinary review and a properly disclosed incentive, then inspect rendered content, aggregate math, enhancement reports and reviewer-facing disclosures. A Rich Results Test pass confirms parseability and some eligibility checks; it does not approve the solicitation practice or promise stars in Search.
Re-audit when the incentive offer changes, a review widget imports another source, the rating calculation changes, a platform policy changes, a reviewer edits a disclosure, or Search Console reports a structured-data problem. Keep rejected review IDs so a later import cannot silently restore them.
Release checklist
- Every review traces to a genuine, item-specific experience.
- No incentive requires or implies a positive sentiment.
- Every material relationship is recorded and disclosed where readers encounter the review.
- Platform terms and applicable legal duties were checked separately from Google markup rules.
- Visible reviews, individual markup and aggregate math use the same eligible record set.
- Imported ratings and self-serving
LocalBusinessorOrganizationreviews are not treated as automatically eligible. - The final rendered page passes mobile, cache, consent and structured-data checks.
- An owner, re-audit date, rollback trigger and evidence location are recorded.
Primary documentation
- Google Search Central: Review snippet structured data
- Google Search Central: General structured data guidelines
- US FTC: Consumer Reviews and Testimonials Rule questions and answers
- US FTC: Soliciting and paying for online reviews
Evidence boundary: Google’s documentation defines eligibility for a Search feature, not a legal safe harbor. FTC material cited here concerns US federal guidance and rules; other laws and platforms may impose additional or different requirements.
Keep learning
Continue this topic
Next in this topic
Product.category and Sale Dates: Feed-to-Schema Map
Earlier in this topic
Discovered—Currently Not Indexed: New-Page Guide
SEO
Ask a question or join the discussion